Military & VA Home Buying
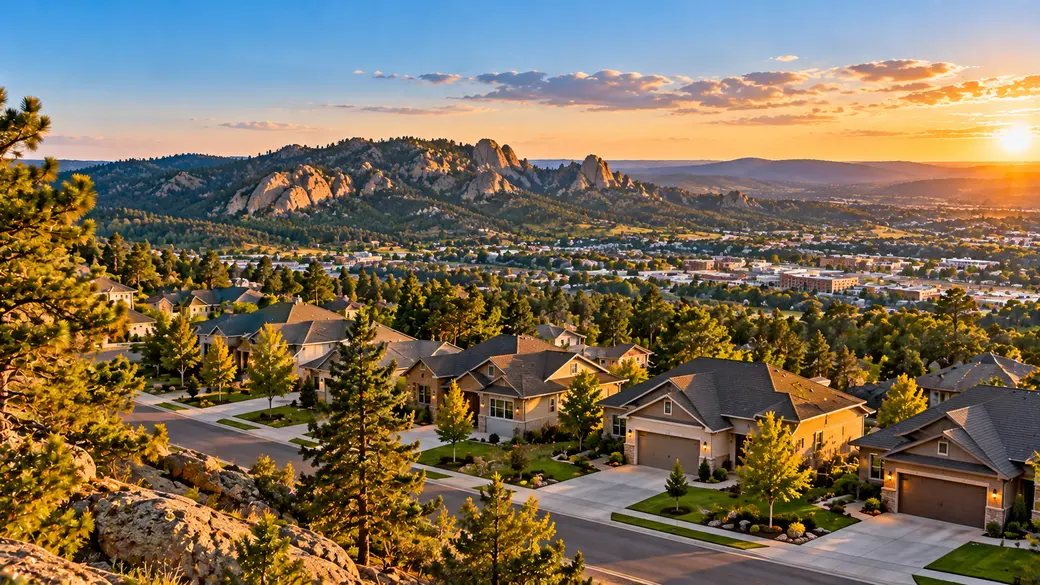
Military & VA home buying in Rapid City, SD requires a plan that fits PCS orders, deployments, and the likely length of your assignment. A purchase can support a smoother move when the payment, location, and future exit options fit your household. This guide explains VA financing, PCS timing, location choices, remote buying, and next-move planning for service members, veterans, and eligible families.
How VA Home Loans Work
A VA home loan is financing for an eligible borrower’s primary residence, with benefits that can reduce upfront cash needs. Begin by requesting a Certificate of Eligibility, or COE, which confirms the VA home loan benefit available to you. The COE is not loan approval, because the lender still reviews income, debts, credit, assets, and the property.
Eligible borrowers with full entitlement may be able to purchase with no down payment, and VA loans do not require private mortgage insurance. Those features can help preserve funds for moving expenses, reserves, and other costs that arise during a PCS.
The VA funding fee is a one-time charge that may apply to a purchase loan. Some borrowers may be exempt, including certain veterans receiving service-connected disability compensation. Confirm the current funding-fee rules, exemption status, and lender requirements through the VA home loan program.
VA financing is intended for a home you plan to occupy as your primary residence. A deployment or new assignment can affect timing, so discuss your reporting date and occupancy plan with a VA-approved lender early.
Military & VA Home Buying Around PCS Orders
Military & VA home buying around PCS orders works best when you begin organizing documents and priorities as soon as a move becomes likely. Waiting for every detail to be finalized can compress your home search, lending process, and closing schedule into an already busy transition. Early preparation gives your household more flexibility if travel, reporting dates, or availability change.
Create a purchase file that includes your COE, current leave-and-earnings statements, bank records, identification, and lender preapproval. Keep your reporting date, temporary-housing plan, target closing window, and preferred communication method in the same place. If one household member may be unavailable because of travel or duty, clarify decision-making and document-signing arrangements before you make an offer.
Buying before arrival can reduce time in temporary housing and give your household a defined place to settle. It also requires confidence in the location, home layout, and daily commute. Waiting until you arrive can make it easier to experience routes, errands, and neighborhood routines firsthand, although it may leave less time before temporary housing ends.
Use live video tours to narrow choices, then focus on homes that meet your practical needs rather than trying to evaluate every available property from a distance.
Choosing a Home Near Your Duty Station
Choosing where to live near your duty station means prioritizing the routine your household will manage on a normal workday. A home that looks ideal during a weekend visit may feel very different when you account for reporting times, gate access, weather, errands, childcare, and one partner handling responsibilities alone.
For households connected to Ellsworth Air Force Base, review official installation information before making commute assumptions. Test likely routes around your expected schedule when possible, ask about alternate approaches, and consider how traffic or seasonal conditions could affect a daily drive. Gate procedures and access patterns can change, so avoid relying on an old route recommendation.
Neighborhood fit also extends beyond commute time. Consider the number of bedrooms, storage needs, outdoor space, nearby services, school preferences, and the amount of upkeep your household can reasonably manage. An established property may offer a useful location or layout, while a newer home may better match your maintenance preferences. Compare each option based on visible condition, records of recent work, and how the space supports your actual routine.
The right choice is personal. Military & VA home buying in Rapid City, SD should reflect your assignment length, household priorities, and ability to adapt if orders change.
First-Time Buyer Essentials for Military Households
A first-time military buyer should build a payment plan around dependable income, Basic Allowance for Housing, savings, and the ongoing cost of ownership. BAH can be an important part of your housing budget, but it should not be the only affordability measure. Include property taxes, insurance, utilities, routine maintenance, moving expenses, and the reserves you want to retain after closing.
Preapproval is an important early step because it helps establish a practical purchase range before you write an offer. Review the expected monthly payment, interest-rate options, lender fees, cash needed at closing, and any funding fee that may apply to your situation. A lender can also explain how military income, allowances, and documentation are evaluated.
Earnest money is a deposit submitted after an offer is accepted to show the buyer’s commitment. Its amount, handling, and refund conditions depend on the purchase contract, so understand those terms before signing. Closing costs are separate from the purchase price and can include lender charges, title services, prepaid taxes, and insurance-related items.
Compare several price points before touring so you can identify a payment range that preserves room for moving costs and reserves. The goal is not to borrow the highest amount available. It is to choose a home payment that stays workable through a PCS transition or changing household expenses.
Buying on a Short Timeline
Buying on a short timeline is possible when your household establishes clear priorities, communication methods, and deadlines early. Remote showings can help you evaluate room flow, storage, visible condition, and the surrounding street without delaying every decision until arrival.
| Task | Practical approach |
|---|---|
| Home selection | Use live video tours and a written list of must-have features |
| Communication | Keep the lender, agent, title contacts, and decision-makers aligned |
| Documents | Store key files securely and confirm signing requirements early |
| Deadlines | Track offer, financing, and closing dates in one shared calendar |
| Final coordination | Confirm travel, access, and possession plans before closing |
Remote closing procedures vary by lender, title provider, transaction details, and applicable requirements. Confirm how documents will be delivered, who may sign, and what identity-verification steps are required well before closing day.
Buy or Rent After a PCS?
Buying after a PCS makes the most sense when ownership supports both your current assignment and a realistic next-step plan. Renting may be the better fit when your tour is short, your timeline is uncertain, or buying would leave your household with limited reserves.
| Factors that may support buying | Factors that may support renting |
|---|---|
| The home fits your expected assignment length | Your assignment may be brief or uncertain |
| You have funds for closing, moving, and ownership costs | You need to preserve savings during the move |
| You can make a confident location decision | You want time to learn commute patterns in person |
| The property remains workable if plans change | A future move could happen sooner than expected |
Future rental potential deserves a cautious review. Consider landlord responsibilities, vacancy periods, repairs, and whether the property would still make financial sense if rental income is lower or delayed. The home should first work as your residence, rather than depending on a future rental plan.
VA Appraisals and Home Inspections
A VA appraisal is not a home inspection because each process has a different purpose. The appraisal helps the lender assess value and determine whether the property meets applicable VA property requirements. It does not provide a detailed assessment of every visible component, maintenance concern, or future repair need.
A home inspection is a separate service selected by the buyer. It provides a closer review of visible systems and conditions, helping you understand maintenance priorities before closing. The findings can help you plan for repairs, request changes within the contract terms, or decide whether the home remains a good fit.
The VA explains that its appraisal is not a guarantee of property value or condition. Review the VA homebuying process guidance with your lender so you understand the requirements that apply to your loan.
For any home, ask focused questions about major systems, visible upkeep, and records of recent work. A tight PCS schedule does not remove the need to understand the property carefully before you commit.
Planning for Your Next Move
Military & VA home buying should include an exit strategy before closing. When orders change, you may sell, keep the home as a rental, or explore whether remaining VA entitlement could support another purchase. Entitlement may be restored after the prior VA-financed home is sold and the loan is paid off, subject to VA rules. Revisit your options before the next PCS instead of assuming every move will follow the same path.
Ashley Reed of Oak & Key Realty helps military families and veterans plan Rapid City purchases around PCS timing, VA financing, remote tours, and realistic next-move options.
FAQ
Is Rapid City a good place to live?
Rapid City can be a practical fit for military households that want access to local services, employment, and varied housing options. The right choice depends on your commute, household budget, preferred daily routine, and expected assignment length. Visit at different times of day when possible, then compare locations based on the needs that matter most to your family.
Is Rapid City expensive?
Rapid City housing costs depend on the property, location, loan terms, insurance, utilities, and maintenance needs. No dated official local cost-of-living figure is cited here, so treat affordability as a household-specific calculation rather than a citywide conclusion. Build your budget around the full monthly payment and retain room for PCS-related expenses.
What salary do you need in Rapid City?
There is no single salary requirement for buying a home in Rapid City. Lender qualification depends on your income, debts, credit profile, available savings, loan terms, and the home’s projected costs. Military buyers should include dependable pay and applicable housing allowance while leaving room for reserves and moving expenses.
Can I use my VA loan more than once?
Yes, eligible borrowers may use VA loan benefits again, subject to available entitlement and lender qualification. Full entitlement can often be restored after a prior VA-financed home is sold and the loan is paid off. Confirm your specific entitlement status with the VA and a VA-approved lender before planning another purchase.
Do I need a down payment with a VA loan?
Eligible borrowers with full entitlement may be able to buy with no down payment. Individual lender requirements, credit factors, and the purchase terms can still affect the loan process. Review your complete cash-to-close estimate instead of assuming that no down payment means no upfront costs.
Can I buy a home before I arrive at my new duty station?
Yes, a buyer can purchase before arriving by using remote tours, secure document sharing, and clear coordination with the lender and transaction parties. This approach works best when the household has defined property priorities and decision-making plans. Confirm signing and closing procedures early because availability can vary by transaction.
Does a VA loan require a home inspection?
No, a VA loan does not require a buyer to obtain a home inspection. The VA appraisal serves a different purpose and does not replace a detailed review of the home’s visible condition. A separate inspection can help buyers understand maintenance concerns before closing.
Recent Posts
GET MORE INFORMATION